
What Happens When A Great Empire Runs Out Of Money
Inside today’s Daily Journal…
Essay: America 2029: The Fourth Turning
The illusion of retail growth
Google goes all in on AI
The Amrize CEO buying spree
Chart Of The Day… ExxonMobil
Today’s Mailbag
Editor’s note: Last month, Porter published a new version of his best-selling book The End of America. The new edition, 2029: The End of America, describes America’s continuing economic, political, and cultural decline. Using the generational framework of the Fourth Turning, his new book describes the underlying forces that are destroying America’s way of life. Here’s an excerpt from the book that explains the root cause of these problems and explains why the final crisis will arrive in 2029.
You know what a country looks like when it runs out of money.
You’ve been living through it for the past 20 years. You’ve just been trained, by the media, to ignore it – not to believe your “lying eyes.”
But you can see it. You saw it in March 2023, when Silicon Valley, First Republic, and Signature Bank all collapsed, with over $500 billion in deposits evaporating in 36 hours. You saw it in the price of eggs, of insurance, of the small house three doors down – things that all now cost twice what they did in 2019. You see it every morning when you look at your pay stub and then look at your grocery receipt and do the math your government refuses to recognize.
None of this is new. It is not new to America. It is not new in the human experience. This – the debasement of the currency – is the oldest story in economics. In fact, I would posit that the lie of paper money is the entire reason the pseudoscience of modern economics, with its focus on econometrics, exists. It is the science of alchemy, the science of lies.
We’ve been told – by our leaders and by our economists – that it’s different this time. It’s different because the dollar is the world’s reserve currency. It’s different because America has the strongest military. It’s different because oil is priced in dollars.
But, of course, it isn’t different at all. This is the way it always happens.
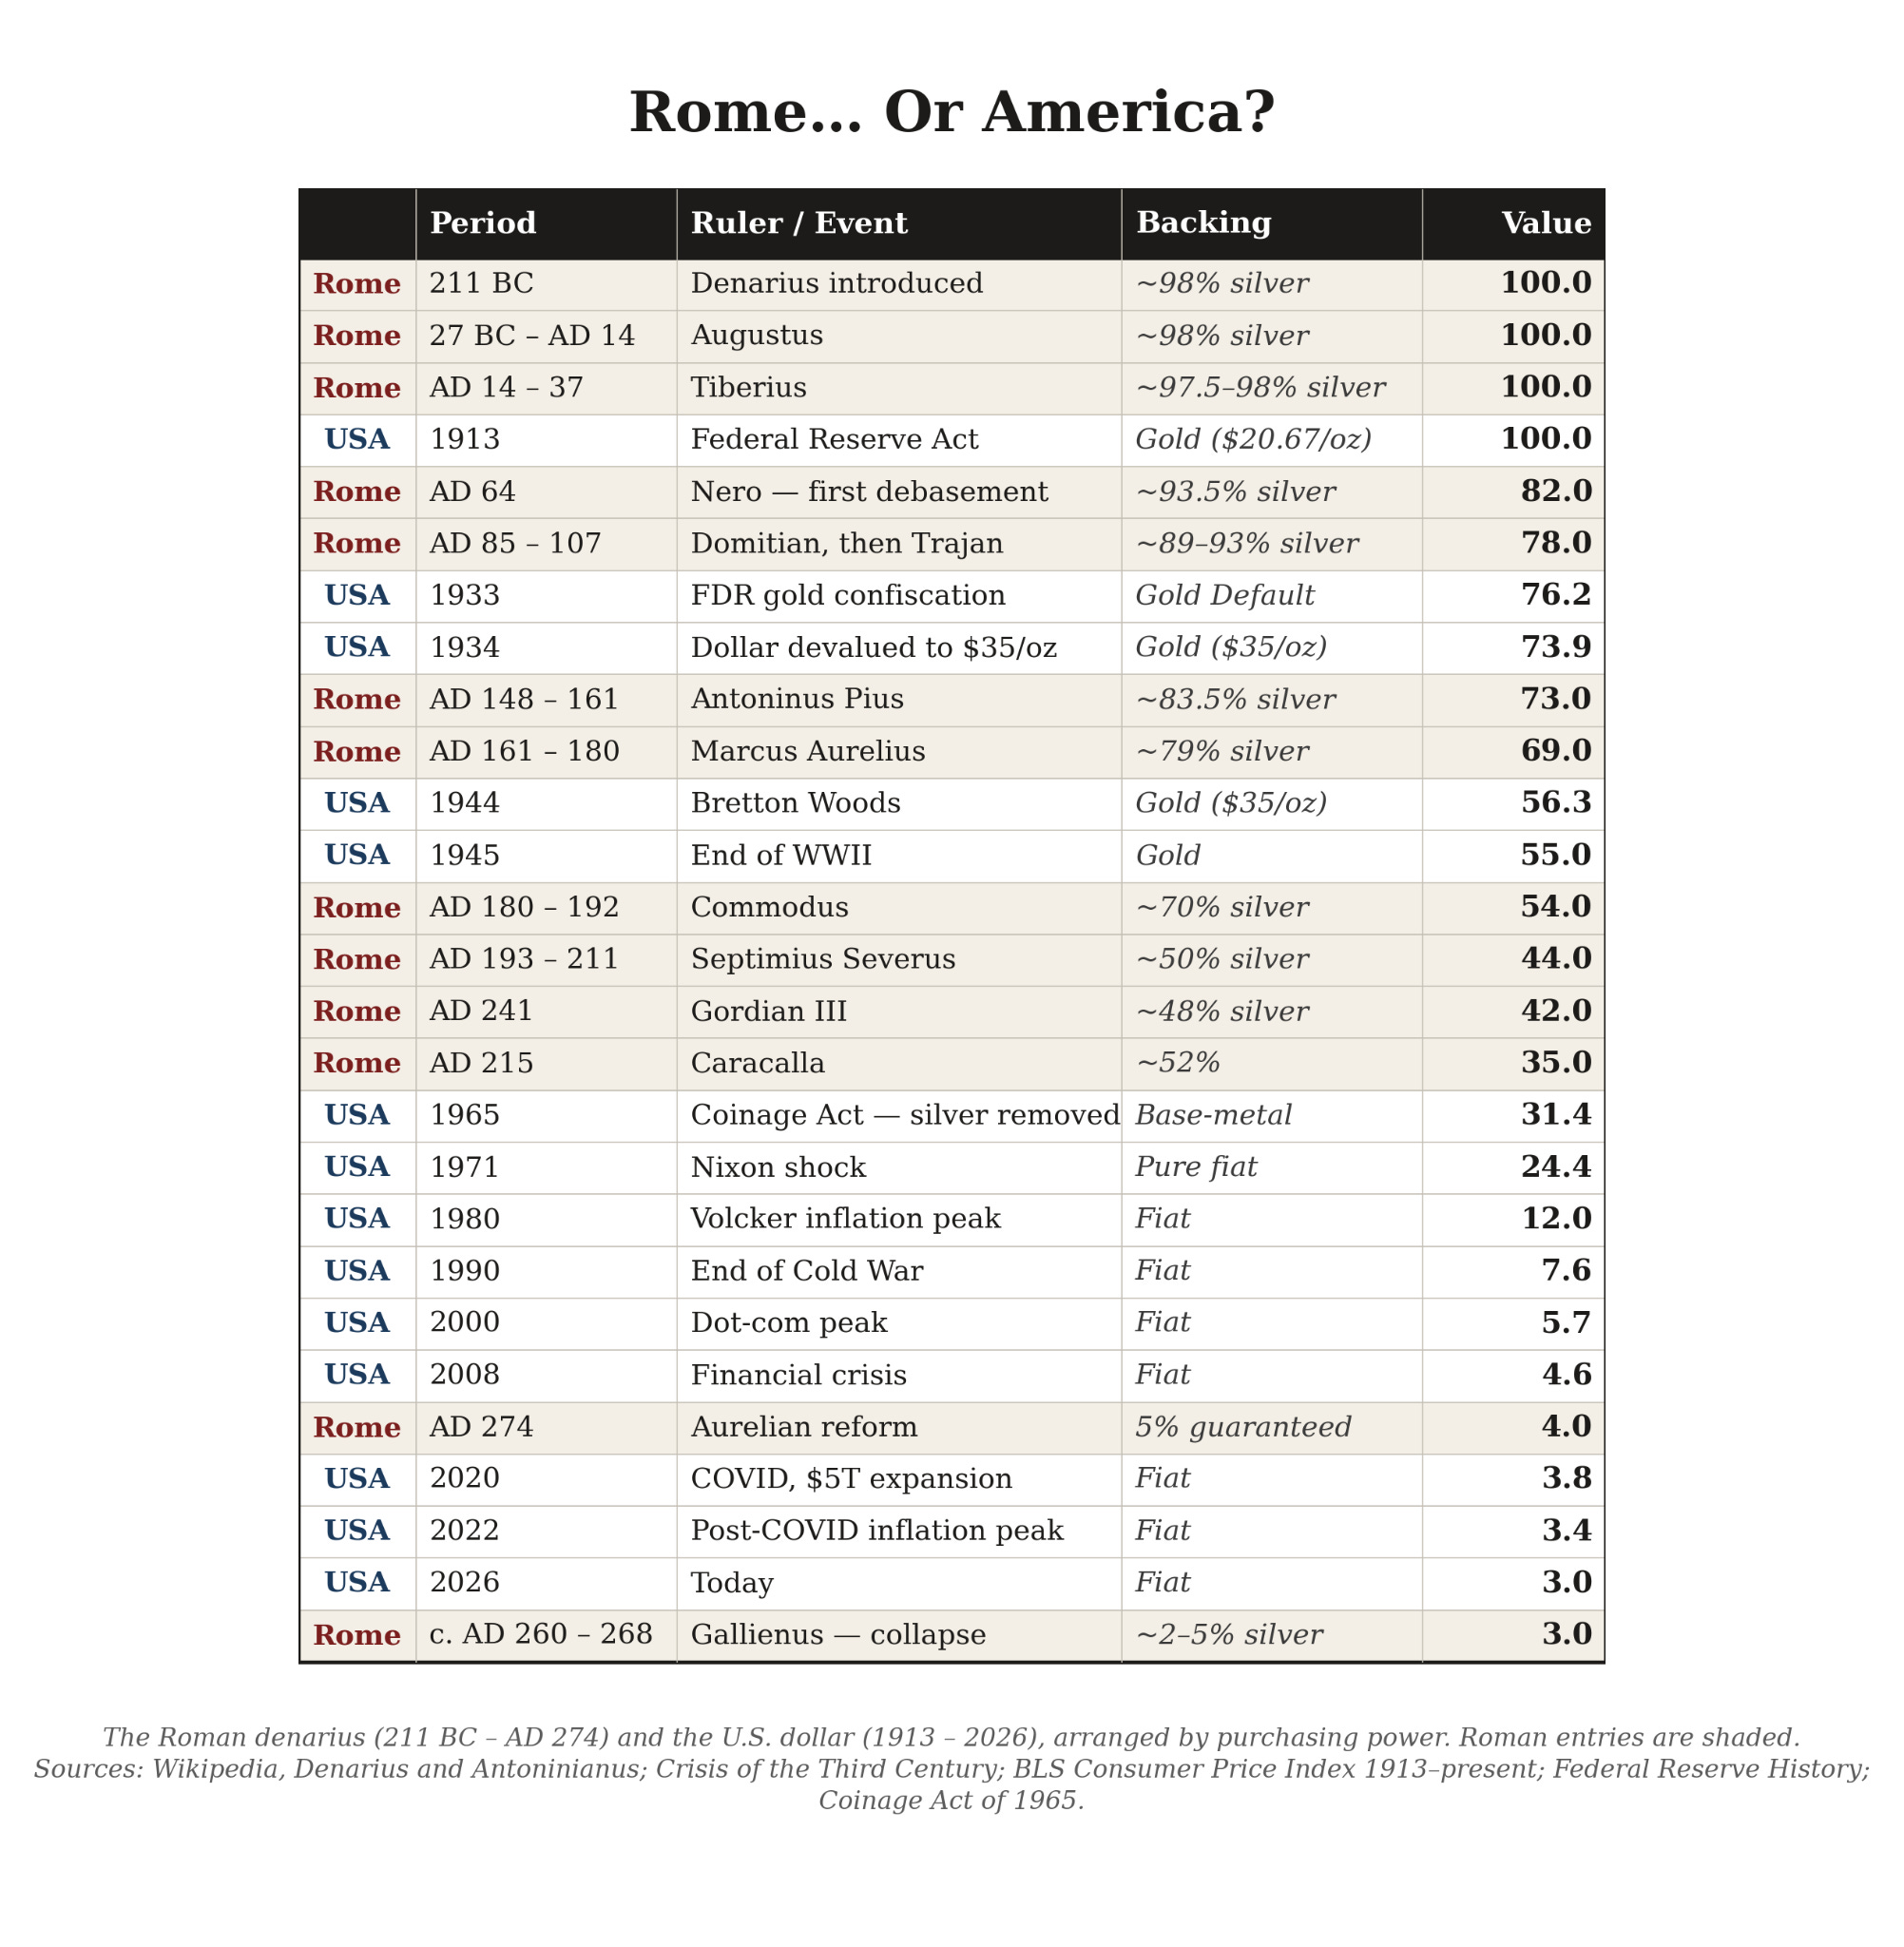
Let me show you.
In 211 BC, in the midst of the Second Punic War, Rome struck its first denarius silver coin.
This was money. It weighed 4.5 grams and assayed between 95% and 98% pure silver. This monetary standard held – astonishingly – for nearly three centuries. Through the conquest of Greece, the wars of Marius and Sulla, the dictatorship of Caesar, the civil wars that followed his murder, and the long reign of Augustus, the denarius stayed honest.
A Roman legionary was paid in denarii. A Syrian farmer selling wheat in the market at Antioch accepted denarii without weighing them. A merchant in Gaul took denarii in exchange for tin. The coin moved frictionlessly through the empire because men who had never seen the emperor’s face trusted his coin. That trust was the empire. Not the legions. Not the roads. Not the aqueducts. The money. Everything else Rome built rested on a sound currency: it enabled an unprecedented amount of global trade and thus created more wealth than the world had ever seen.
But then, slowly at first, Rome stopped keeping its promise.
In AD 64 – the year of the Great Fire – Nero called in the old denarii and restruck them. He cut the weight from 84 coins per Roman pound to 96 and dropped the fineness from roughly 98% to about 93.5%. It was the first debasement of any consequence in more than 250 years.
The emperor needed money to rebuild the city and his endless spectacles. The easiest way to get it was to call in the old coins and strike new ones with a little more copper mixed in. The soldiers didn’t notice. The farmers didn’t notice. The merchants in Gaul didn’t notice. The silver content fell by five percentage points and the empire went on functioning as though nothing had changed.
Domitian briefly raised the fineness back toward the old standard in the 80s AD but soon, the debasement continued. Under Trajan, in AD 107, the silver content was quietly cut again, from roughly 93.5% down to about 89%. Under Marcus Aurelius – the philosopher-king, the Stoic, the man whose Meditations we still read in graduate seminars on leadership – the coin fell to roughly 79% fine to pay for the Marcomannic wars. Under his son Commodus, the weight was cut again – by one-eighth – and the fineness slipped to around 70%.
Then came the Severans. Septimius Severus doubled the size of the army and the legionary’s base pay and paid for it the only way he could: by cutting the silver content of the denarius to roughly 50%.
In AD 215, his son Caracalla tried something new. He minted a coin called the antoninianus, which claimed to be two denarii but contained only about 1.6 denarii worth of silver. It was a 52% fine coin weighing 5.1 grams that bought 25% more than the silver in it justified. It was the ancient world’s first explicit, legislated fiat premium. The state declared, by edict, that the coin was worth more than the metal it contained.
How do you think that worked out…?
The floor gave way. Under Gordian III in the 240s, fineness was already below 50%. Under Gallienus, in the 260s, the antoninianus became a copper slug with a thin silver wash – roughly 2% to 5% silver, and even that mostly cosmetic, applied to the surface so the coin would look like silver until it wore off in a few months of circulation.
In a little over 200 years – from Nero’s first cut in AD 64 to the bottom under Gallienus around AD 268 – the Roman silver coin went from roughly 98% silver to under 5%. And the men in Rome who ordered the debasement – every single one of them – told the same lie.
These lies should sound familiar to you. This is temporary. This is necessary. We must “break the glass” to save the country.
The cycle was finally broken, after the fact, by two emperors who understood that the empire could not be held together without an honest coin. Aurelian in AD 274 tried to standardize a new coin guaranteed at 5% silver – marked XXI on the reverse, an explicit promise of one part silver to 20 of bronze. Twenty years later, in AD 293–294, Diocletian carried out the full reform: a new pure silver coin called the argenteus, struck at 96 to the pound and roughly 90% to 95% fine – the first honest silver coin Rome had issued in more than two centuries.
But it did not work for long. By AD 301, Diocletian had to double the argenteus’ face value to keep up with inflation. Within a few years he was issuing the Edict on Maximum Prices and threatening death to merchants who charged what their goods actually cost.
And here is the part of the history that 99% of economists never understand. By debasing the coinage, the political class built an economy that could not function on honest money.
The legions had to be paid. The grain dole in Rome had to be distributed. The client kings at the frontier had to be bribed. But with a broken exchange system, there was no honest way to afford the obligations of the Roman state. The only way to keep the machine running was to debase the coins. And that, in turn, created still more demand for graft. It wasn’t long before the entire empire ran on graft.
Sound familiar?
I am describing a political system that makes so many promises – to its soldiers, to its citizens, to its allies – that the promises can only be kept by breaking the underlying promise on which all the others depended.
Here is what the merchants in Gaul did when the silver content fell below 50%. They stopped taking Roman coins. They went back to barter. They weighed out actual silver bullion on a scale. They traded oxen for wheat and wheat for iron and iron for wine. The imperial economy – which had been the most sophisticated commercial network in human history – reverted to the Bronze Age inside of a single century.
When the coin dies, the economy (the trade networks, the capital investments) dies with it. Not in theory. In practice. At the market in Antioch. On the docks at Ostia. In the grain fields of Egypt.
And when the economy dies, the culture dies. The roads fall apart because no one is paid to maintain them. The aqueducts silt up because the engineers have gone home. The legal code — the Corpus Juris Civilis, the greatest gift Rome ever gave the world — becomes a museum piece because no court can enforce it.
Rome did not fall because barbarians crossed the Rhine. Rome fell because its coin became a lie. When the coin failed, Rome failed.
This is the template for every great power that has ever debased its currency to fund promises it could not keep. This is what happened in France under Philip IV. This is what happened to Spain under the Habsburgs, who drowned in silver from Potosí and died broke anyway. This is what happened to Weimar Germany. To Hungary in 1946. To Zimbabwe. And to Argentina eight times over.
This is what will happen to the United States of America in the year 2029.
Tell me what you think of today’s Journal: porterstansberrydirect@gmail.com
Good investing,
Porter Stansberry
Stevenson, Maryland
The SpaceX Text Message You Were Never Supposed to See
A Wall Street insider just revealed that the SpaceX IPO may be coming sooner than expected.
Here’s how to get pre-IPO exposure — before the frenzy starts.
Use this 4-letter ticker symbol and just $50.
👉 Watch now and get the ticker now, free.
Editor’s Note: Keep in mind, we only accept advertising from publishers we know to offer well-researched ideas vetted by a legal team, excellent customer service, and reasonable refund policies. Crowdability is one such partner. We do not, however, under any circumstances make any representations about their investment ideas or strategies, nor will we warrant them as equal to our own. We do recognize that the markets are tempestuous and, at times, ideas that we may not endorse prove valuable.
3 Things To Know Before We Go…
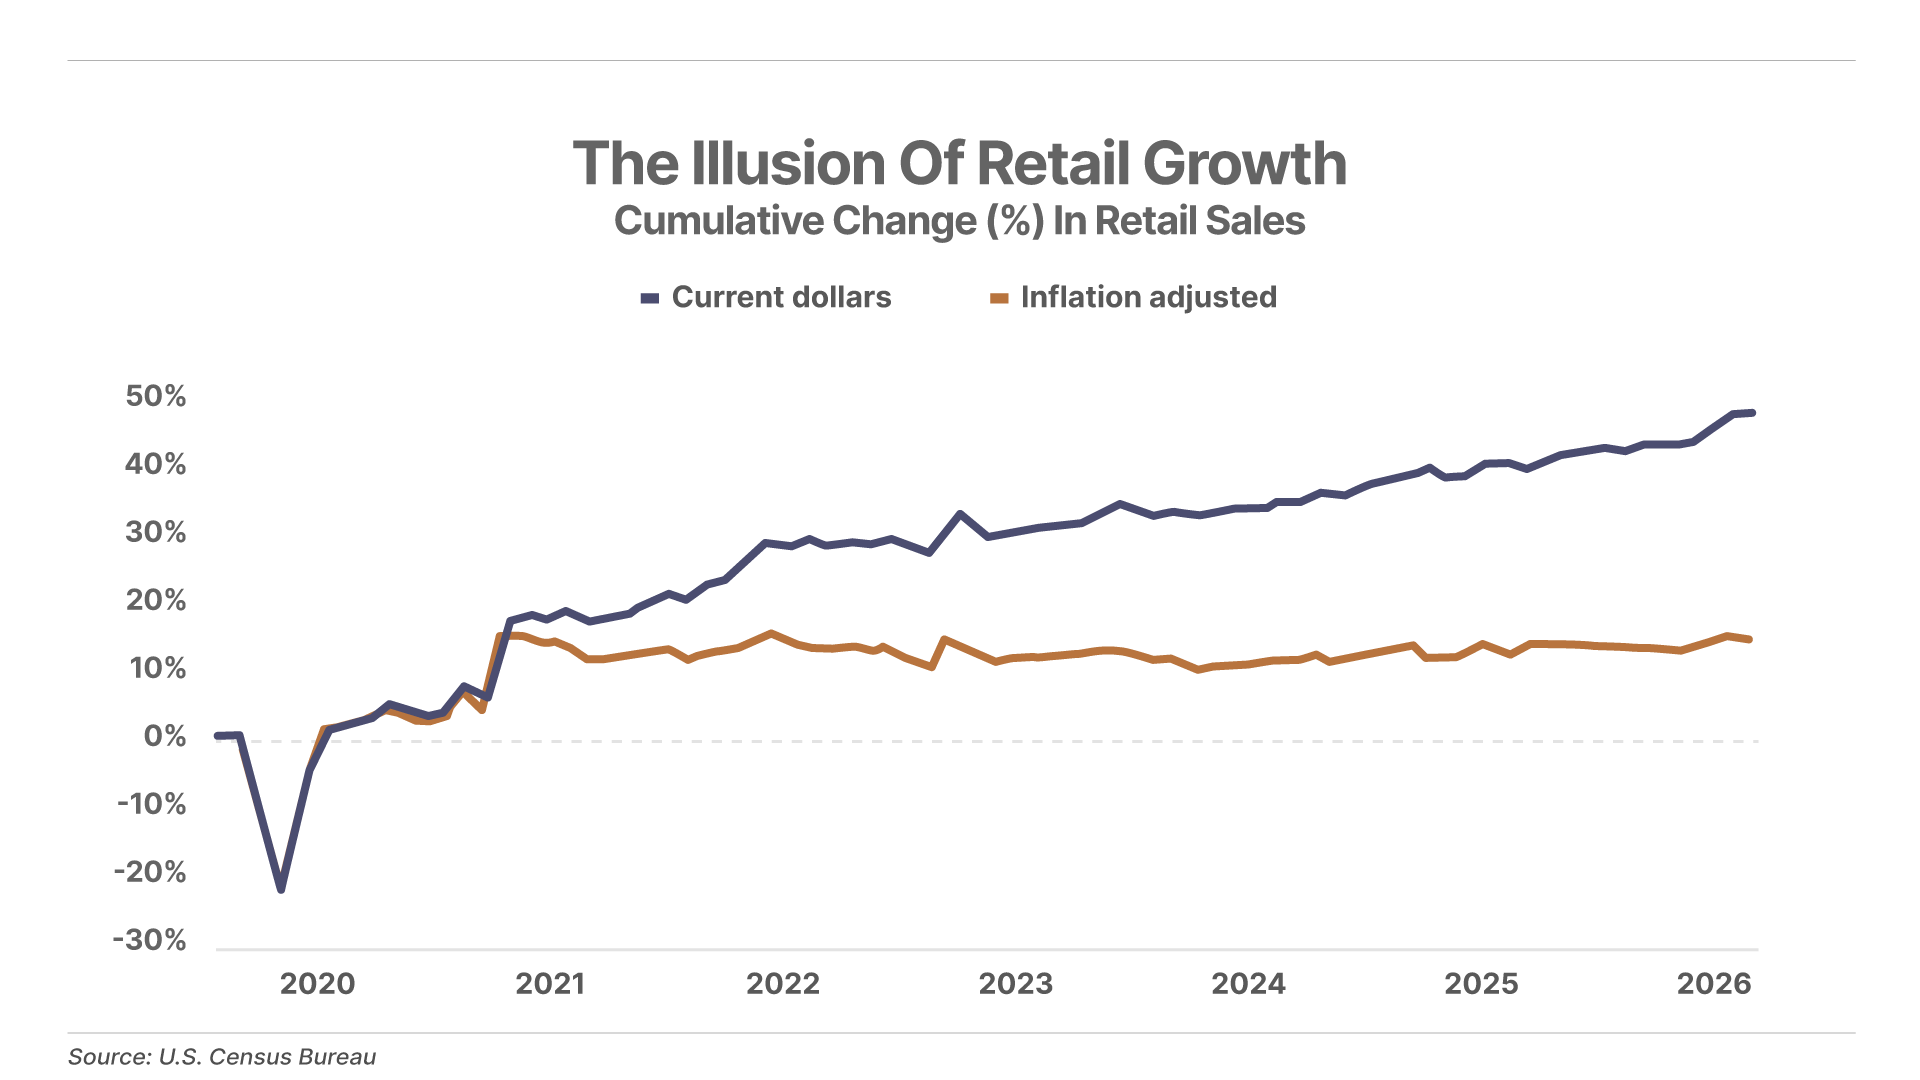
1. The dollar illusion. Between April 2021 and April 2026, nominal retail sales rose 24.3% – but in real terms, growth was essentially zero. Americans aren’t buying more – they’re paying more for the same basket. With nearly 7% mortgage rates, 4% inflation, and a dollar that buys roughly 30% less than it did in early 2020, lower-income consumers are running out of gas – and, yes, the cost of that is up 50% in the last three months as well.
2. Google goes big on AI agents. At its annual I/O developer conference yesterday, Google unveiled the Gemini 3.5 model family, a redesigned Search bar – billed as the biggest Search upgrade in nearly 30 years – and Gemini Spark, a 24/7 personal AI agent that lives across Gmail, Docs, and Sheets to execute multi-step tasks on your behalf. And it’s steadily gaining AI-platform market share.
3. Big insider buying in Amrize. Jan Jenisch has been buying the dip, investing more than $2.3 million in Amrize (AMRZ) shares so far this week. The CEO of the North American building solutions firm, a December Complete Investor recommendation, has now invested more than $63 million of his own money into the stock since the company was spun off from global construction firm Holcim last June. Most of these purchases were made near the current share price of around $50, a level where Janisch clearly sees tremendous value.
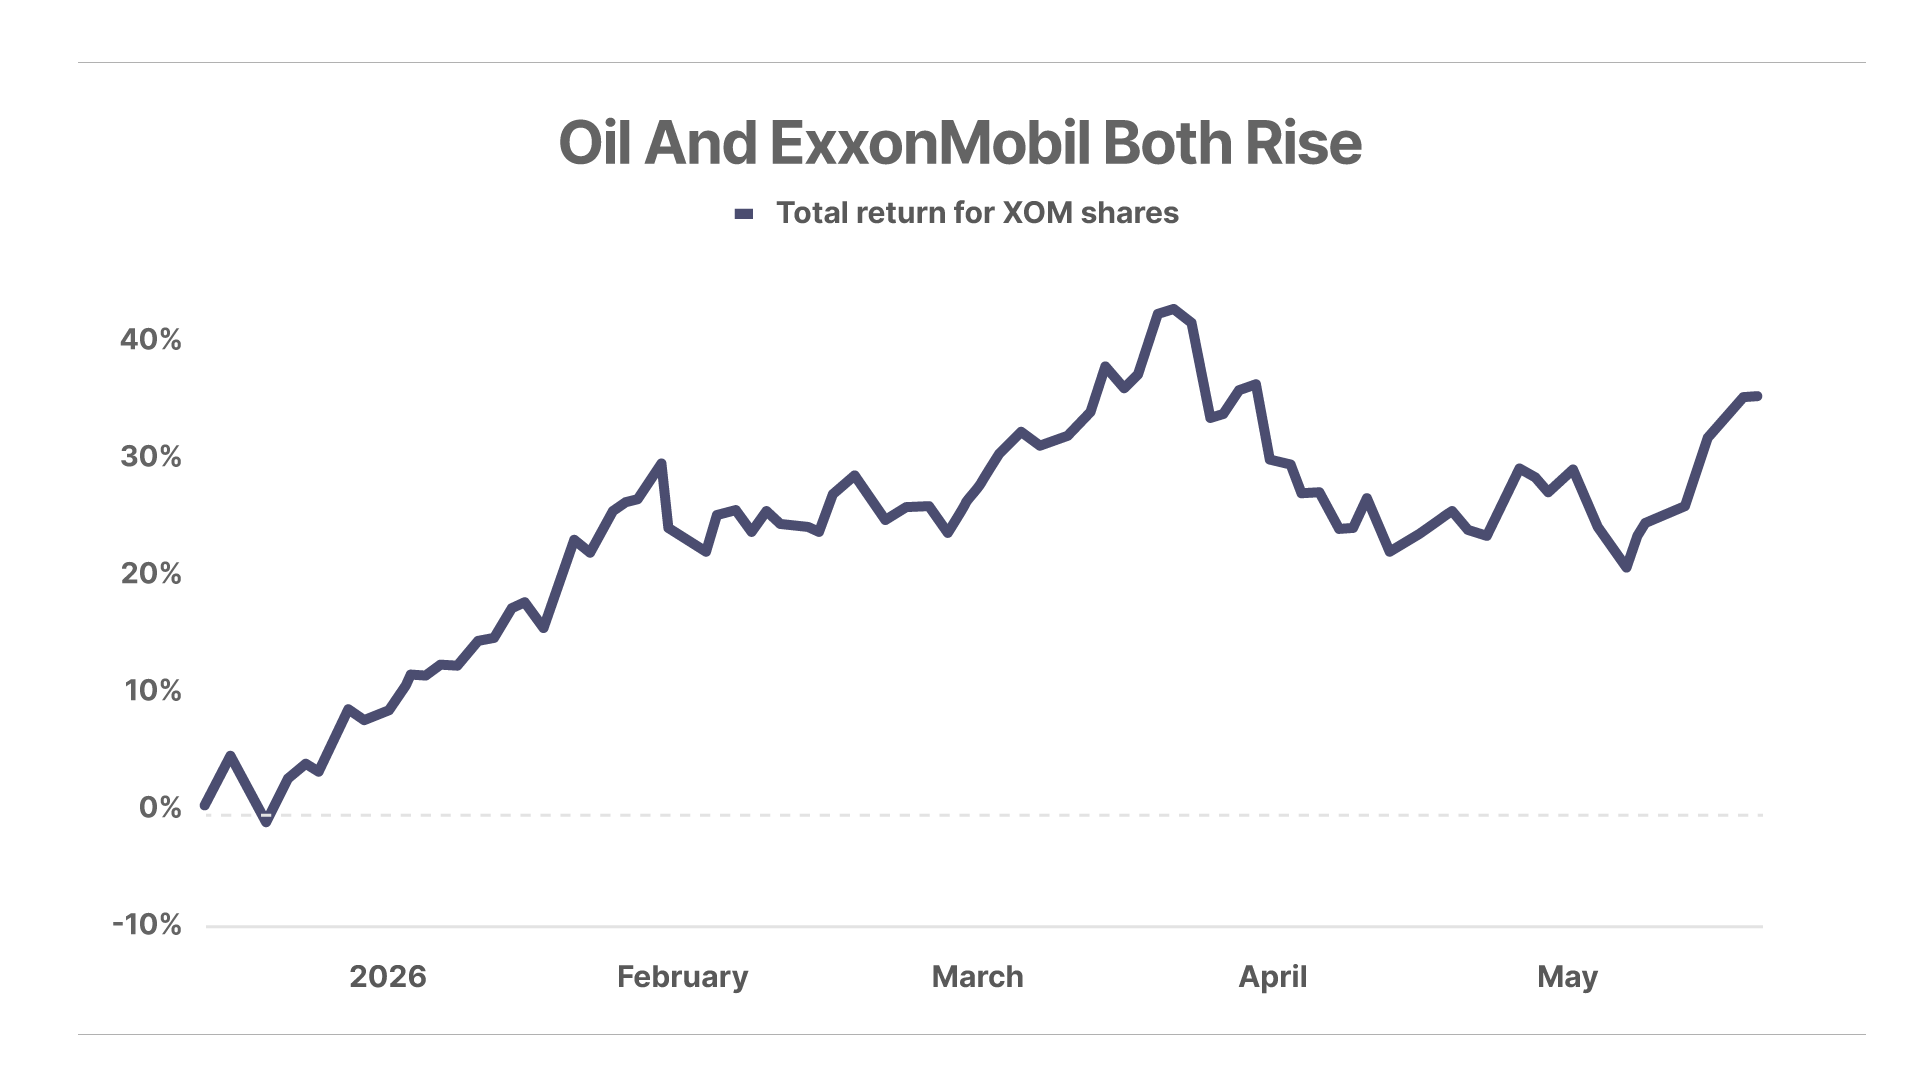
Chart Of The Day… ExxonMobil (XOM)
The Strait of Hormuz closure has driven shares of Complete Investor recommendation ExxonMobil (XOM) up for seven straight sessions – closing 1.3% higher yesterday and pushing its year-to-date gains to 33%. Now with experts cautioning that the full effects of the closure haven’t yet hit the market, inventories could plummet and drive oil prices – and XOM shares – even higher.
Mailbag
“Warren’s Mistakes”
Tom G. writes:
Porter,
I am reading your book, Warren’s Mistakes. Very good, and you make such a compelling argument. I have two questions:
Why do you think Warren decided to change his buying practices after such a long, successful time?
Have you heard any feedback from either Warren or any of his many spokespersons about what you have been writing about him in recent years?
Just curious!!
Porter Comment:
I explain it in the book. Warren is a collector. When his collection became so large that he could no longer promise investors an economic return, he chose to keep his collection. A very human decision, in my opinion.
Yes, many years ago, when I told Warren that I was writing this book, he declined to be involved.
“Some Confusion”
Ralph G. writes:
Hi Porter,
I have been one of your long-time followers from the early days of Stansberry Research, and am currently a lifetime subscriber to Complete Investor and Tech Frontiers.
I have been following your Daily Journal and viewed the most recent video presentation featuring you, Erez, Marty, and Ross. For some time now, you have emphasized that once the 10-year Treasury yield goes above 4%, you should exercise caution. And once it surpasses 5%, well, that is the red line for which you have told us to get out of stocks.
Yet in the most recent issue of Complete Investor, it is pretty much business as usual, with new “buy” recommendations. There is a bit of a disconnect in this for me.
Either you think:
These buys are relatively immune to the crash you think is coming – which they most likely are not
You’re thinking we have six or more months before the crash occurs so let’s squeeze out some gains while we can
You’re thinking something else, and if so, I’m curious what that is
I usually buy what you recommend and have done well (not sure I’ve ever thanked you). And I love your writing style. However, in your current Complete Investor, it seems like you’re asking us to roast marshmallows on the edge of an approaching forest fire.
My discomfort is not only because I’m 76 years old (that is part of it for sure). Just doesn’t make sense to move into a house when the roof appears to be caving in.
I would appreciate any comments you might have.
Porter Comment: Ralph –
You’re exactly correct: our most recent recommendation is “roasting marshmallows” on the edge of a forest fire.
But we have a recommended list that incorporates many different levels of risk. Everything from ultra-safe stocks like Mitsui & Co. (MITSY), ExxonMobil (XOM), and Chubb (CB) to things like Uber Technologies (UBER), Alphabet (GOOG), and Nvidia (NVDA) that are clearly more speculative.
We believe our most recent recommendation, like Google and Nvidia, has an extremely valuable moat and will play an incredible role in the artificial intelligence build-out over the next decade – as we detail in the newsletter.
It is easy to see the risk of buying stocks when there’s so much speculative froth in the markets. It is harder to see the risks of missing out on the “melt-up.” In Japan, in the 1980s, stocks went to 90x earnings.
My point: we can’t know the future, but we can help you prepare to thrive, no matter what happens. To me, that means always giving you all of the information I’d most want if our roles were reversed.
Our last issue’s recommendation – while perhaps too risky and aggressive for you – could easily turn out to be our most valuable insight this year.
“Your Thoughts On The Great Taking”
Don H. writes:
I’ve previously heard rumblings along these lines but dismissed them. Now I’m not so sure …
David Rogers Webb, the former hedge fund manager of Varus and author of The Great Taking, describes how property rights of securities have been corrupted and that individuals are not the rightful owners of their securities. When the engineered collapse occurs, the banks will assume ownership… the great taking.
Are you familiar with this? And what is your understanding of what the current bank regulations allow?
Porter Comment: In the U.S., investors are beneficial owners of securities through a broker or bank in “street name.” That doesn’t mean the broker “owns” the security. It doesn’t appear on their balance sheet and they can’t use it as collateral, etc. Webb conflates record ownership, beneficial ownership, and creditor claims in insolvency. U.S. law recognizes property interests through intermediaries. In other words, the legal structure is not “you own nothing,” but rather “you own through a legal and operational chain that introduces intermediary risk.” What’s the intermediary risk? It is not a seizure of your property. The risk is, in a severe intermediary failure, rehypothecation, commingling, custody errors, or insolvency mechanics could make recovery slower, messier, or less complete than retail investors assume. That is a legitimate concern, but it is incredibly rare and nothing at all like Webb’s apocalyptic framing.
Let me give you a real world example.
MF Global, the commodities brokerage run by former New Jersey Governor Jon Corzine, collapsed in October 2011 after a bad bet on European debt. About $1.2 billion in customer funds went missing when the firm violated segregation rules by dipping into customer accounts. Corzine famously told Congress he didn’t know where the money was. Customers eventually recovered funds through a trustee-managed bankruptcy under SIPC (Securities Investor Protection Corporation) and CFTC (Commodity Futures Trading Commission) oversight, though recovery was slow. The firm broke the law and the customers were harmed. Corzine, by the way, never faced a criminal charge and only paid a $5 million fine. There’s no justice in America. But that doesn’t mean that your brokerage firm can simply seize your assets.